UK Parents Open Pension Accounts for Toddlers and Babies, Citing Long-Term Growth
An increasing number of families across the UK are initiating personal pension schemes for their infant and toddler children, embarking on a long-term financial strategy to build significant retirement wealth.
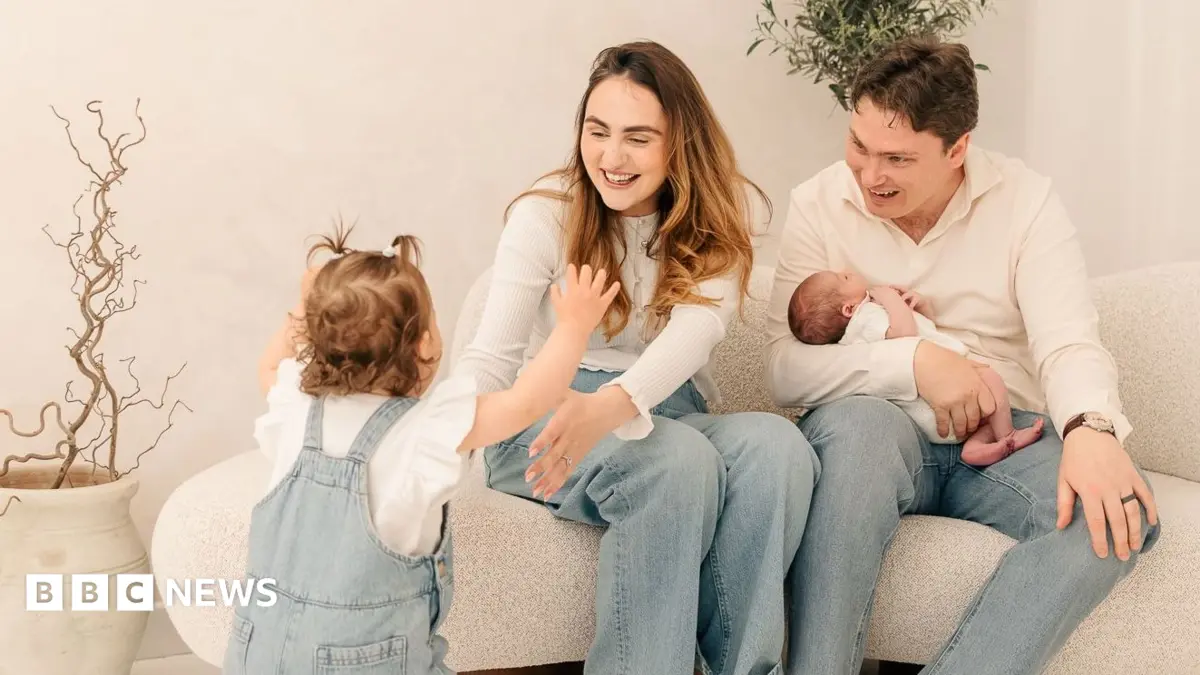
For instance, one couple, Mark and Laura, are reportedly investing £100 each month into pension accounts for their two children, aged two years and nine months respectively. Their motivation stems from understanding the power of compound interest over an extended period, aiming to secure a substantial financial foundation for their children's future.
These junior self-invested personal pensions (SIPPs) operate similarly to adult SIPPs, offering tax relief on contributions. Parents can invest up to £2,880 annually into these accounts, which is then topped up by the government to £3,600 through tax relief. This mechanism effectively means a £2,880 parental contribution immediately becomes £3,600 in the child's pension pot.
While the funds remain inaccessible until the child reaches retirement age, currently 55, and potentially later depending on future legislative changes, advocates of this approach highlight the immense potential for growth. Financial models suggest that even modest consistent contributions, compounded over six decades or more, could result in substantial seven-figure sums, significantly alleviating future financial pressures for the beneficiaries.